about me
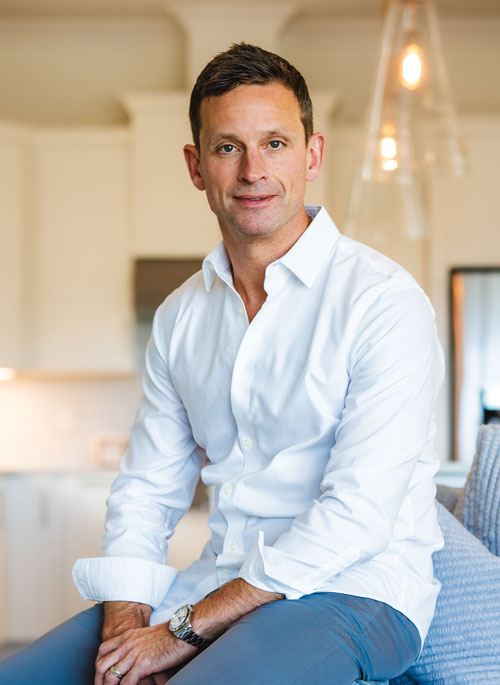
Hello, I’m Tyler Duncan, Producing Branch Manager at Supreme Lending.
I started my career in mortgage lending in 2008 as a Loan Officer and Team Lead before opening my own branch. Since then, I’ve had the privilege of helping more than 1,500 families buy or refinance their homes. Every loan represents a milestone in someone’s life, and being part of that journey is what still motivates me every day.
I work across a wide range of loan programs, from primary residences and investment properties to new construction, condos, manufactured homes, HELOCs, and reverse mortgages. No two clients are the same, and my approach is always tailored to fit each borrower’s goals. Clear communication, accessibility, and transparency are the foundation of how I work. My goal is simple: make the lending process smooth, efficient, and even enjoyable, because homeownership should feel exciting, not overwhelming.
Achievements
I’m honored to be recognized among the Top 1% of Loan Officers in the nation by Mortgage News Daily and to have earned Supreme Lending President’s Club recognition every year from 2016 through 2025. These milestones reflect the consistency, teamwork, and commitment it takes to deliver the level of service my clients expect.
Community & Memberships
I serve as Vice President of my local BNI chapter, collaborating with professionals who share a commitment to excellence, connection, and community growth. Relationships are at the center of everything I do — both in business and in life.
Hobbies
Outside of work, I’m a lifelong sports enthusiast. I grew up playing football and basketball, which taught me the value of competition, discipline, and relentless consistency—qualities that I’ve carried into my career. These days, watching sports is how I unwind. Whether it’s football Sundays, college hoops, or baseball season, the lessons from the field—teamwork, drive, and focus—remain my daily inspiration.
Outside the Office
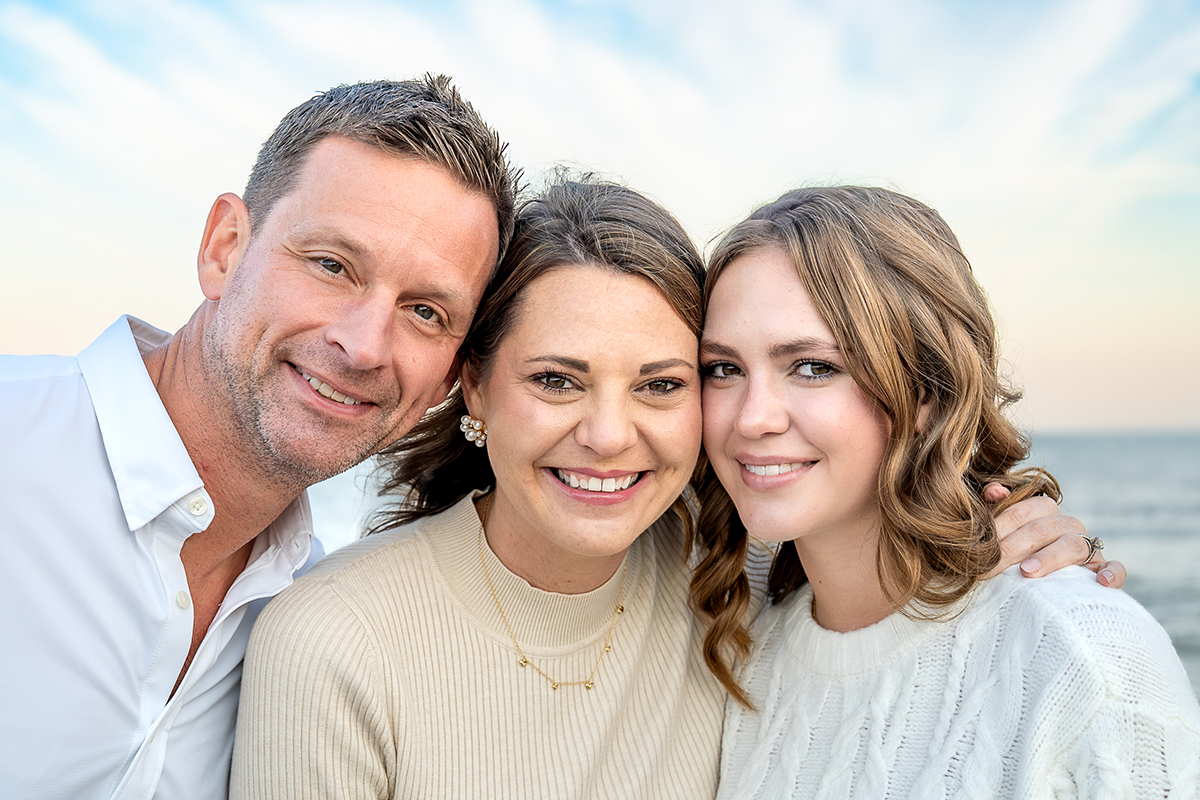
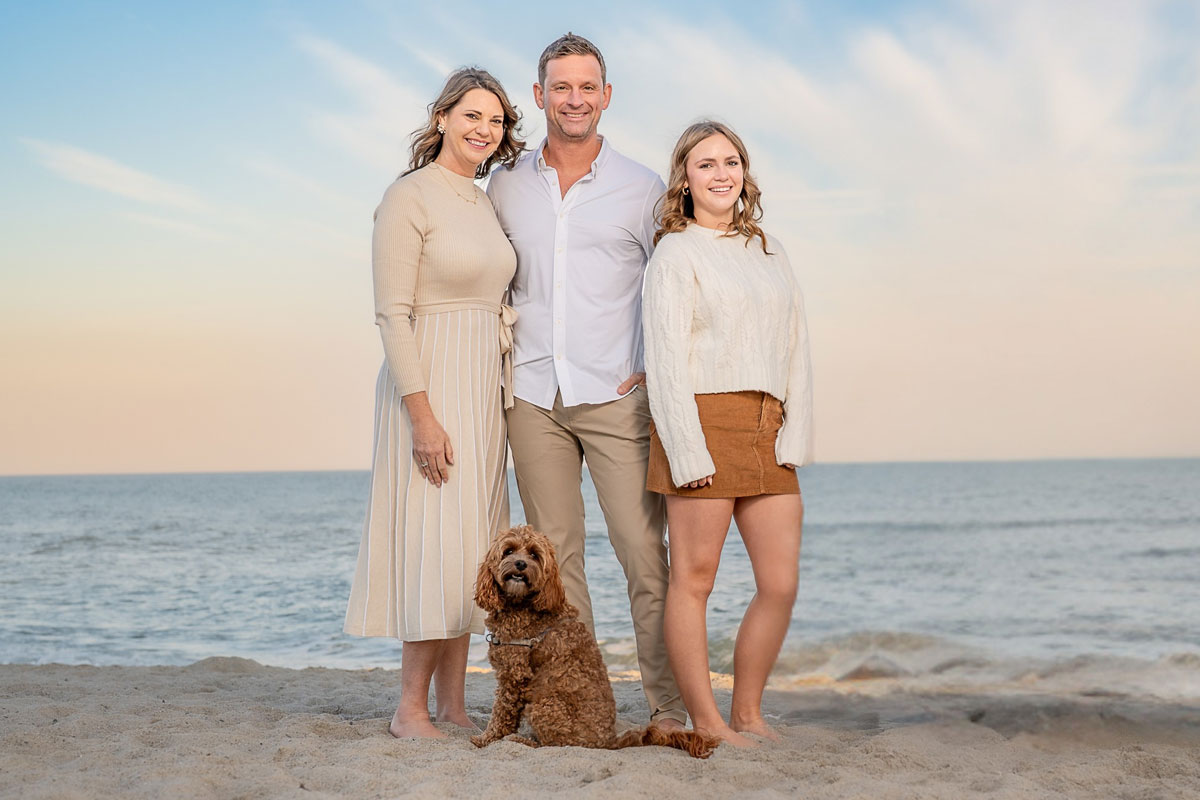
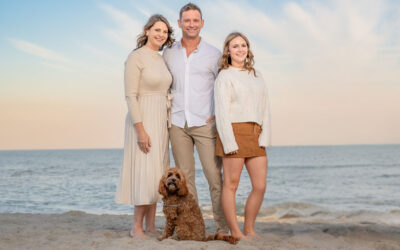
My greatest pride is my family. My wife and I will celebrate our 20th anniversary this year, and not many couples can say they work side by side every day — I’m beyond blessed to have her as my marketing manager and partner in this business. We share the same commitment to serving our clients and building something meaningful together.
We’re also incredibly proud parents to our teenage daughter, who is an avid swimmer and golfer and is beginning college tours as she pursues her dream of a future in medicine. Watching her dedication and ambition grow has been one of the most rewarding parts of our lives. Family is the foundation behind everything I do. The same care, commitment, and long-term mindset I bring to my work comes from the life we’re building together at home.
Delivering the Slam Dunc Experience from Coast to Coast
Mortgage guidance built on speed, clarity, and trust
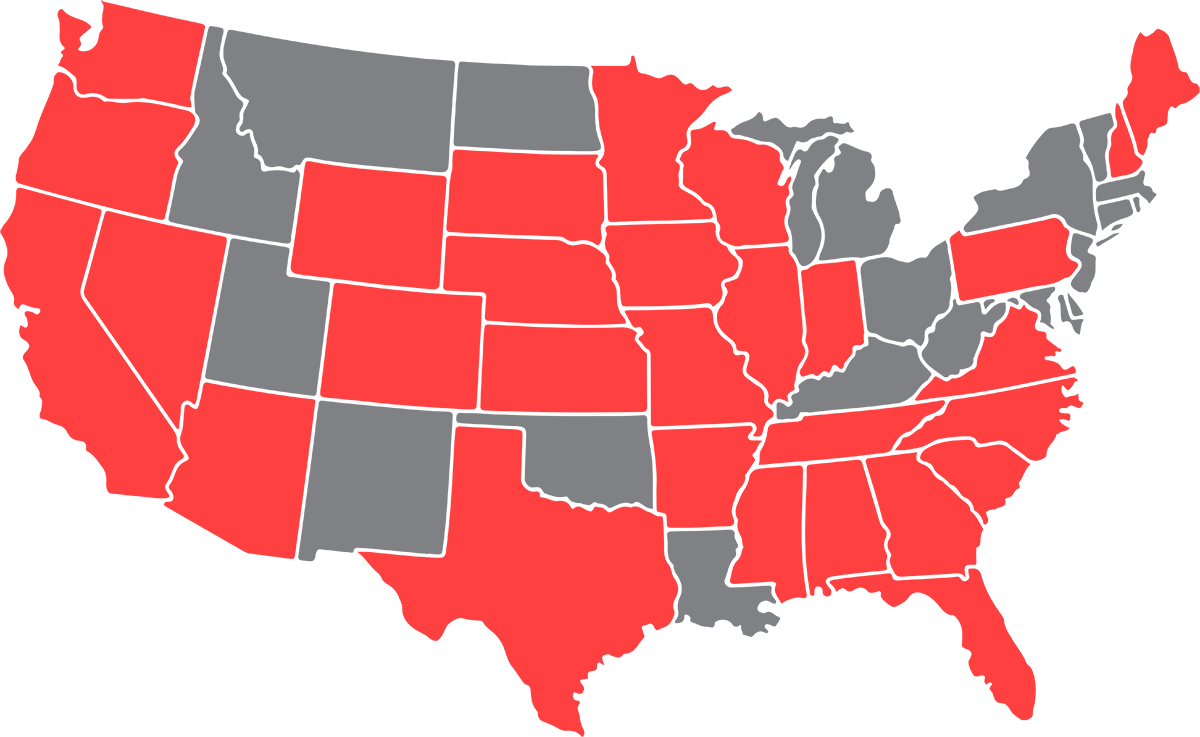
Licensed across 20+ states so wherever you’re buying or refinancing, your loan is handled with precision.
Mortgage guidance built on speed, clarity, and trust
Licensed across 20+ states so wherever you’re buying or refinancing, your loan is handled with precision.
Licensed in:
- Alabama
- Arizona
- Arkansas
- Colorado
- Florida
- Illinois
- Indiana
- Kansas
- Maine
- Minnesota
- Mississippi
- Missouri
- Nebraska
- Nevada
- New Hampshire
- North Carolina
- Oregon
- Pennsylvania
- South Carolina
- Tennessee
- Virginia
- Washington
- Wisconsin
- Wyoming
benefits of becoming a home owner
Benefits of Owning a Home
Why Homeownership Matters
Homeownership offers more than a place to live — it provides stability, freedom, and a foundation for long-term goals. Owning a home allows families to put down roots, build equity, and create consistency in a space that supports both present needs and future plans. It’s an investment not only in property, but in lifestyle and opportunity.
Whether you’re purchasing your first home, upgrading, downsizing, or investing, owning real estate gives you the ability to shape your environment and build something lasting. With clear guidance and thoughtful preparation, buyers can move forward with confidence and clarity.
Delivering the Slam Dunc Experience from coast to coast means making the process straightforward and efficient, helping families feel informed, prepared, and supported from start to finish.
A Smart Move for Your Future
Homeownership as a Long-Term Strategy
A home is often one of the most meaningful financial decisions a person makes. Beyond providing shelter, it can serve as a tool for long-term wealth building, financial stability, and generational opportunity. Real estate gives buyers the ability to invest in their future while creating a place to grow, gather, and build memories.
Every buyer’s situation is different. Whether the goal is stability, expansion, investment, or flexibility, the right mortgage strategy makes a difference. My role is to guide clients through the options with transparency and clarity so they can make informed decisions that support their bigger picture.
That’s what delivering the Slam Dunc Experience from coast to coast looks like — confident decisions, smooth execution, and a path forward that fits your life.
loan programs
Conventional Loans
Conventional loans are not backed by the government and are one of the most popular loan options for qualified buyers. They offer flexible terms and can be used for primary residences, second homes, and some investment properties.
Read More
Key Features
– Down payments as low as 3% for first-time buyers
– Competitive fixed and adjustable rates
– No upfront government insurance fees
– Option to remove PMI once you reach 20% equity
Eligibility & Guidelines
– Credit score typically 620 or higher
– Debt-to-income ratio up to 45%
– Available for primary residences, second homes, or investment properties
Ideal For
– Borrowers with good credit and stable income
– Homebuyers looking for flexibility and low long-term costs
– Homeowners refinancing for better terms
FHA Loans

Read More
Key Features
– Down payments as low as 3.5%
– Credit scores as low as 580 may qualify
– Competitive fixed rates
– Assumable loans for easier resale
Eligibility & Guidelines
– Must occupy the home as a primary residence
– FHA-approved appraisal and property standards required
– Upfront and monthly mortgage insurance apply
Ideal For
– First-time homebuyers
– Borrowers with limited credit history or smaller savings
– Families looking for affordable entry into homeownership
USDA Loans
Overview
USDA loans offer zero-down financing for homes in eligible rural and suburban areas, helping families enjoy affordable homeownership outside major city limits.
Read More
Key Features
– 100% financing (no down payment)
– Competitive fixed interest rates
– Low mortgage insurance costs
– Flexible credit requirements
Eligibility & Guidelines
– Property must be in a USDA-eligible area
– Income limits apply based on household size
– Primary residence only
Ideal For
– Buyers seeking affordable homeownership in rural or suburban areas
– First-time buyers who meet income and location criteria
Read More
Key Features
– Down payments as low as 3% for first-time buyers
– Competitive fixed and adjustable rates
– No upfront government insurance fees
– Option to remove PMI once you reach 20% equity
Eligibility & Guidelines
– Credit score typically 620 or higher
– Debt-to-income ratio up to 45%
– Available for primary residences, second homes, or investment properties
Ideal For
– Borrowers with good credit and stable income
– Homebuyers looking for flexibility and low long-term costs
– Homeowners refinancing for better terms
Read More
Key Features
– Down payments as low as 3.5%
– Credit scores as low as 580 may qualify
– Competitive fixed rates
– Assumable loans for easier resale
Eligibility & Guidelines
– Must occupy the home as a primary residence
– FHA-approved appraisal and property standards required
– Upfront and monthly mortgage insurance apply
Ideal For
– First-time homebuyers
– Borrowers with limited credit history or smaller savings
– Families looking for affordable entry into homeownership
Read More
Key Features
– 100% financing (no down payment)
– Competitive fixed interest rates
– Low mortgage insurance costs
– Flexible credit requirements
Eligibility & Guidelines
– Property must be in a USDA-eligible area
– Income limits apply based on household size
– Primary residence only
Ideal For
– Buyers seeking affordable homeownership in rural or suburban areas
– First-time buyers who meet income and location criteria
Jumbo Loans
When your dream home requires financing beyond conforming loan limits, Jumbo Loans provide the solution. We offer tailored jumbo financing to help you move forward with confidence.
Read More
Key Features
– Loan amounts exceeding conforming limits
– Competitive interest rates
– Flexible terms and structures
– Options for primary residences, vacation homes, and investment properties
Eligibility & Guidelines
– Strong credit and income required
– Larger down payment often needed (typically 10–20%)
– Appraisal and reserve requirements apply
Ideal For
– Buyers purchasing high-value homes
– Borrowers with complex financial portfolios
VA Loans
VA loans are designed for veterans, active-duty service members, and eligible surviving spouses. With zero down payment and no monthly mortgage insurance, they’re one of the best paths to homeownership for those who’ve served our country.
Read More
Key Features
– 0% down payment
– No private mortgage insurance (PMI)
– Competitive interest rates
– Flexible credit and debt guidelines
Eligibility & Guidelines
– Must have a valid Certificate of Eligibility (COE)
– Must occupy the home as a primary residence
Ideal For
– Veterans and active-duty service members
– Eligible surviving spouses
– Buyers seeking affordable, no-down-payment options
DSCR Loans
Debt Service Coverage Ratio (DSCR) loans are designed for real estate investors who prefer to qualify based on rental income instead of personal income. It’s a flexible path for growing your investment portfolio.
Read More
Key Features
– Qualification based on property cash flow
– No tax returns or personal income documentation required
– Suitable for short-term or long-term rentals
– 30-year fixed or adjustable terms available
Eligibility & Guidelines
– Minimum DSCR typically 1.0 or higher
– Down payments around 20–25%
– Minimum credit score around 660
Ideal For
– Investors seeking simpler qualification
– Buyers expanding rental portfolios
Read More
Key Features
– Loan amounts exceeding conforming limits
– Competitive interest rates
– Flexible terms and structures
– Options for primary residences, vacation homes, and investment properties
Eligibility & Guidelines
– Strong credit and income required
– Larger down payment often needed (typically 10–20%)
– Appraisal and reserve requirements apply
Ideal For
– Buyers purchasing high-value homes
– Borrowers with complex financial portfolios
Read More
Key Features
– 0% down payment
– No private mortgage insurance (PMI)
– Competitive interest rates
– Flexible credit and debt guidelines
Eligibility & Guidelines
– Must have a valid Certificate of Eligibility (COE)
– Must occupy the home as a primary residence
Ideal For
– Veterans and active-duty service members
– Eligible surviving spouses
– Buyers seeking affordable, no-down-payment options
Read More
Key Features
– Qualification based on property cash flow
– No tax returns or personal income documentation required
– Suitable for short-term or long-term rentals
– 30-year fixed or adjustable terms available
Eligibility & Guidelines
– Minimum DSCR typically 1.0 or higher
– Down payments around 20–25%
– Minimum credit score around 660
Ideal For
– Investors seeking simpler qualification
– Buyers expanding rental portfolios
100% Financing
Read More
Key Features
– Buyers with strong income but limited savings
– First-time homebuyers
– Certain eligible borrowers
Key Benefits:
– No down payment required
– Reduced upfront costs
– Competitive loan terms
Renovation Loans
Read More
Key Features
– One loan, one closing
– Low down payment options
– Finance cosmetic or structural renovations
– Available for FHA (203k) or Conventional (HomeStyle) borrowers
Eligibility & Guidelines
– Minimum credit score typically 620+
– Licensed contractors required for all work
– Home must be primary residence for FHA; flexible for Conventional
Ideal For
– Buyers purchasing homes needing updates
– Current homeowners refinancing to renovate
One Time Close
Read More
Key Features
· One-Time Close Option – Combines your construction and permanent mortgage into one convenient loan with a single closing.
· Two-Time Close Option – Provides separate loans for construction and permanent financing, giving you more control over final terms and rates.
· Interest-Only Payments During Construction – Pay only for the funds drawn during your build.
· Flexible Program Options – Available for FHA, VA, Conventional, and Jumbo loans.
· Local Montana Expertise – Our team understands local markets, builders, and property types throughout Montana.
One-Time Close vs. Two-Time Close
|
Feature
|
One-Time Close
|
Two-Time Close
|
|---|---|---|
|
Closings
|
One combined closing for construction and permanent financing
|
Two separate closings for added flexibility
|
|
Interest Payments
|
Interest-only during construction
|
Interest-only during construction
|
|
Rate Lock
|
Lock your rate before construction begins
|
Choose a new rate when converting to the permanent loan
|
|
Simplicity
|
One approval, one set of closing costs
|
Flexibility to requalify and adjust loan terms
|
|
Ideal For
|
Borrowers seeking convenience and predictability
|
Borrowers wanting flexibility and control
|
Eligibility & Guidelines
· Available for primary residences, second homes, and select investment properties
· Must use a licensed and approved builder (self-builds may require additional review).
· Minimum down payment and credit score requirements vary by loan program.
· Property must meet appraisal and construction standards.
· Construction periods typically last up to 12 months.
Ideal For
· Borrowers planning to build a custom home.
· Homeowners looking for a simple or flexible financing structure.
· Buyers who want to lock in their rate early or customize loan terms after construction.
Why StonePath Mortgage
At StonePath Mortgage, we’re proud to serve communities with the personal touch of a local lender and the resources of a trusted mortgage partner. Our construction lending specialists provide clear communication, hands-on guidance, and dependable support from blueprint to move-in day—so you can focus on building the home you’ve always envisioned.
Next Steps
Contact StonePath Mortgage today to explore your construction loan options. Our team will help you compare One-Time and Two-Time Close programs, explain qualification details, and create a plan tailored to your build.
Read More
Key Features
– Buyers with strong income but limited savings
– First-time homebuyers
– Certain eligible borrowers
Key Benefits:
– No down payment required
– Reduced upfront costs
– Competitive loan terms
Read More
Key Features
– One loan, one closing
– Low down payment options
– Finance cosmetic or structural renovations
– Available for FHA (203k) or Conventional (HomeStyle) borrowers
Eligibility & Guidelines
– Minimum credit score typically 620+
– Licensed contractors required for all work
– Home must be primary residence for FHA; flexible for Conventional
Ideal For
– Buyers purchasing homes needing updates
– Current homeowners refinancing to renovate
Read More
Key Features
· One-Time Close Option – Combines your construction and permanent mortgage into one convenient loan with a single closing.
· Two-Time Close Option – Provides separate loans for construction and permanent financing, giving you more control over final terms and rates.
· Interest-Only Payments During Construction – Pay only for the funds drawn during your build.
· Flexible Program Options – Available for FHA, VA, Conventional, and Jumbo loans.
· Local Montana Expertise – Our team understands local markets, builders, and property types throughout Montana.
One-Time Close vs. Two-Time Close
|
Feature
|
One-Time Close
|
Two-Time Close
|
|---|---|---|
|
Closings
|
One combined closing for construction and permanent financing
|
Two separate closings for added flexibility
|
|
Interest Payments
|
Interest-only during construction
|
Interest-only during construction
|
|
Rate Lock
|
Lock your rate before construction begins
|
Choose a new rate when converting to the permanent loan
|
|
Simplicity
|
One approval, one set of closing costs
|
Flexibility to requalify and adjust loan terms
|
|
Ideal For
|
Borrowers seeking convenience and predictability
|
Borrowers wanting flexibility and control
|
Eligibility & Guidelines
· Available for primary residences, second homes, and select investment properties
· Must use a licensed and approved builder (self-builds may require additional review).
· Minimum down payment and credit score requirements vary by loan program.
· Property must meet appraisal and construction standards.
· Construction periods typically last up to 12 months.
Ideal For
· Borrowers planning to build a custom home.
· Homeowners looking for a simple or flexible financing structure.
· Buyers who want to lock in their rate early or customize loan terms after construction.
Why StonePath Mortgage
At StonePath Mortgage, we’re proud to serve communities with the personal touch of a local lender and the resources of a trusted mortgage partner. Our construction lending specialists provide clear communication, hands-on guidance, and dependable support from blueprint to move-in day—so you can focus on building the home you’ve always envisioned.
Next Steps
Contact StonePath Mortgage today to explore your construction loan options. Our team will help you compare One-Time and Two-Time Close programs, explain qualification details, and create a plan tailored to your build.
REVIEWS
FAQs
Why should you get Pre-Qualified?
Getting pre-qualified for a mortgage is a great first step to kickstart your homebuying journey. Pre-qualification gives you a picture of how much you may afford based on your credit, income, and debt. It helps you determine your budget, understand estimated monthly payments, find the right loan program, strengthen your offer, and save time.
What is the difference between Conventional and FHA loans?
There are many differences between conventional and FHA loans. In this portion we will outline some of the major differences for you.
On FHA loans, the minimum down payment is 3.5%. On a conventional loan, the down payment may be as low as 3% depending on a consumers credit scores. Additionally, the money on a conventional loan must be “seasoned” (60 days in the bank) prior to purchasing the home or be proceeds from the sale of your existing home.
A FHA loan requires an upfront Mortgage Insurance payment (MIP); a Conventional loan does not. Both do require monthly Mortgage Insurance premiums based on the LTV.
The taxes will be the same on either type of loan. A common mistake is that people believe is their taxes will vary depending on the loan they choose. The title company that closes the loan submits the taxes directly to the lender. If you reside in an attorney state, your representation is the one who orders the tax certificate from the appraisal district. Taxes reported to the lender will be included in your monthly loan payment. There is no mark-up or service charge over and above the actual tax amount.
Homeowner’s insurance works the same as taxes. You pay the lender for your policy amount on a monthly basis. The lender will escrow this amount and send it to your insurance company at the end of the year when renewal is due.
Interest rate differences will vary depending on the lender you choose. Most importantly, ALWAYS ask for the lowest rate for the type of loan you are obtaining.
The principal and interest portion of the payment is calculated by configuring the loan amount (MIP rolled into the balance on FHA) and term into an amortization schedule to calculate the payment amount. Ask your Supreme Lending representative for additional information on conventional and FHA loans.
What are closing costs?
Closing costs are paid upfront for necessary expenses associated with purchasing a home. When
applying for a loan, you’ll receive a Loan Estimate outlining these settlement charges for added fees like loan origination, appraisal, credit report, title insurance, document preparation, prepaid interest, and other miscellaneous fees.
Which loan program is suitable for me?
There is no one-loan-fits-all. Supreme Lending offers a wide range of mortgage programs to choose from depending on what may be the most beneficial for your circumstances. Your Loan Officer may present different scenarios to see what aligns with your goals—whether a fixed-rate or adjustable-rate mortgage, or a Conventional loan or government-backed loan, such as FHA, VA, or USDA.
What goes into a monthly mortgage payment?
What documentation may be needed?
When you apply for a home loan, several documents are requested to confirm your ability to make monthly mortgage payments. Here are a few items you will likely will need to submit:
• Income history and employment verification from the past two years, such as tax returns, W-2s, and 1099s (if applicable)
• Asset statements for bank, retirement, and brokerage accounts
• Monthly debt payments, including any outstanding loans and credit cards
• Records of rent payments, divorce, bankruptcy, or foreclosure
Why should you get Pre-Qualified?
Getting pre-qualified for a mortgage is a great first step to kickstart your homebuying journey. Pre-qualification gives you a picture of how much you may afford based on your credit, income, and debt. It helps you determine your budget, understand estimated monthly payments, find the right loan program, strengthen your offer, and save time.
What is the difference between Conventional and FHA loans?
There are many differences between conventional and FHA loans. In this portion we will outline some of the major differences for you.
On FHA loans, the minimum down payment is 3.5%. On a conventional loan, the down payment may be as low as 3% depending on a consumers credit scores. Additionally, the money on a conventional loan must be “seasoned” (60 days in the bank) prior to purchasing the home or be proceeds from the sale of your existing home.
A FHA loan requires an upfront Mortgage Insurance payment (MIP); a Conventional loan does not. Both do require monthly Mortgage Insurance premiums based on the LTV.
The taxes will be the same on either type of loan. A common mistake is that people believe is their taxes will vary depending on the loan they choose. The title company that closes the loan submits the taxes directly to the lender. If you reside in an attorney state, your representation is the one who orders the tax certificate from the appraisal district. Taxes reported to the lender will be included in your monthly loan payment. There is no mark-up or service charge over and above the actual tax amount.
Homeowner’s insurance works the same as taxes. You pay the lender for your policy amount on a monthly basis. The lender will escrow this amount and send it to your insurance company at the end of the year when renewal is due.
Interest rate differences will vary depending on the lender you choose. Most importantly, ALWAYS ask for the lowest rate for the type of loan you are obtaining.
The principal and interest portion of the payment is calculated by configuring the loan amount (MIP rolled into the balance on FHA) and term into an amortization schedule to calculate the payment amount. Ask your Supreme Lending representative for additional information on conventional and FHA loans.
What are closing costs?
Closing costs are paid upfront for necessary expenses associated with purchasing a home. When
applying for a loan, you’ll receive a Loan Estimate outlining these settlement charges for added fees like loan origination, appraisal, credit report, title insurance, document preparation, prepaid interest, and other miscellaneous fees.
Which loan program is suitable for me?
There is no one-loan-fits-all. Supreme Lending offers a wide range of mortgage programs to choose from depending on what may be the most beneficial for your circumstances. Your Loan Officer may present different scenarios to see what aligns with your goals—whether a fixed-rate or adjustable-rate mortgage, or a Conventional loan or government-backed loan, such as FHA, VA, or USDA.
What goes into a monthly mortgage payment?
What documentation may be needed?
When you apply for a home loan, several documents are requested to confirm your ability to make monthly mortgage payments. Here are a few items you will likely will need to submit:
• Income history and employment verification from the past two years, such as tax returns, W-2s, and 1099s (if applicable)
• Asset statements for bank, retirement, and brokerage accounts
• Monthly debt payments, including any outstanding loans and credit cards
• Records of rent payments, divorce, bankruptcy, or foreclosure
Mortgage Process
01
Conversation
The first step is crucial and sets the stage for your home buying experience. You and your loan officer will discuss your short and long-term financial goals so we can customize a loan strategy fit for you and your family.
02
Application
The goal of completing an application is to gather as much information possible so your loan officer can determine all the available loan programs available.
03
Pre-Qualification
At this stage, your loan officer will share how many homes you can afford, what your monthly payment will be, and how much money you will need.
04
Documents
This is where we need your help! By submitting your income and asset documentation upfront allows us to fly through the underwriting process.
05
Found a Home
Once you find a home and the seller accepts your offer we’ll order an appraisal and begin processing and underwrite your loan.
06
Final Approval
The underwriter reviews the appraisal, and your income/asset documents to verify you meet all the
conditions for final approval.
07
Closing day
Our in-house closing department works with the attorney to assemble the final paperwork. Everything we do leading up to this point ensures a smooth and exciting experience.
Mortgage Calculator
Results received from this calculator are designed for comparative purposes only, and accuracy is not guaranteed. Supreme Lending is not responsible for any errors, omissions, or misrepresentations. This calculator does not have the ability to pre-qualify you for any loan program. Qualification for loan programs may require additional information such as credit scores and cash reserves which is not gathered in this calculator. Information such as interest rates and pricing are subject to change at any time and without notice. Additional fees such as HOA dues are not included in calculations. All information such as interest rates, taxes, insurance, PMI payments, etc. are estimates and should be used for comparison only. Supreme Lending does not guarantee any of the information obtained by this calculator.
Results received from this calculator are designed for comparative purposes only, and accuracy is not guaranteed. Supreme Lending is not responsible for any errors, omissions, or misrepresentations. This calculator does not have the ability to pre-qualify you for any loan program. Qualification for loan programs may require additional information such as credit scores and cash reserves which is not gathered in this calculator. Information such as interest rates and pricing are subject to change at any time and without notice. Additional fees such as HOA dues are not included in calculations. All information such as interest rates, taxes, insurance, PMI payments, etc. are estimates and should be used for comparison only. Supreme Lending does not guarantee any of the information obtained by this calculator.
Mortgage Insights
Tyler Duncan: Helping Homebuyers Navigate the Mortgage Landscape
Whether you’re buying, refinancing, or investing, navigating the mortgage process can feel overwhelming without the right guidance. My goal is to simplify that journey and help clients move forward with clarity and confidence — no matter where they’re buying. As...
A Step-by-Step Look at the Mortgage Process with Tyler Duncan
Securing a home loan is one of the most important financial decisions you’ll make. Whether you’re buying, refinancing, or investing, understanding the process brings confidence and clarity to every step. My goal is to simplify that journey and make sure clients feel...
Tyler Duncan: Delivering the Slam Dunc Experience from Coast to Coast
Hello — I’m Tyler Duncan, Producing Branch Manager at Supreme Lending. Since entering the mortgage industry in 2008, I’ve had the privilege of helping more than 1,500 families buy or refinance their homes. Every loan represents a milestone in someone’s life, and being...
get in contact
Let’s start the process of getting you Pre-Qualified
Tyler Duncan
Producing Branch Manager
NMLS #221548
1209 Culbreth Drive, Suite 228
Wilmington, NC 28405
Branch: (910) 348-0488
Hours of Operation: Open 24 Hours